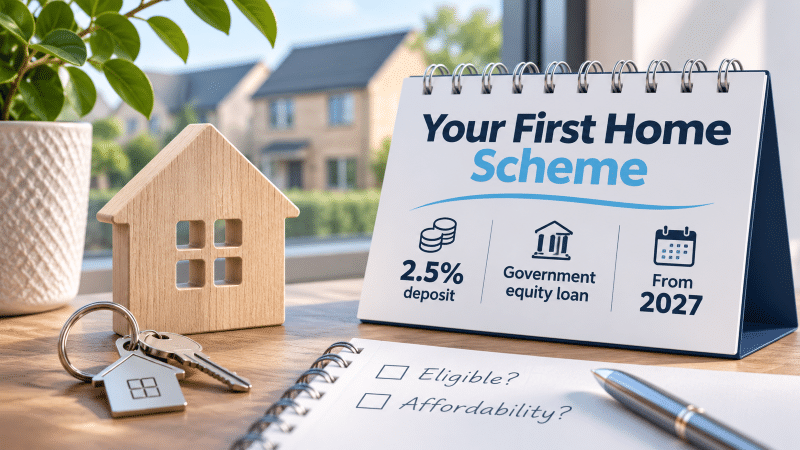
Your First Home is a new government scheme designed to help eligible first-time buyers purchase a property in England.
For years, many prospective buyers have focused on one obstacle.
Saving enough money for a deposit.
The 2026 Budget introduced a new approach that could reduce this initial barrier.
Under the planned scheme, qualifying buyers could purchase a new-build property with a deposit starting at just 2.5%.
However, a smaller deposit does not automatically mean a cheaper home.
Understanding the government equity loan is just as important as understanding the mortgage.
At a Glance: Your First Home Scheme 2027
According to the government’s latest guidance:
- Minimum deposit: 2.5% of the property purchase price.
- Government equity loan: 20% of the purchase price.
- Interest-free period: First five years.
- Eligible properties: Qualifying new-build homes in England.
- Income limits: Normally £110,000 outside London and £140,000 within London.
- Applications: Expected to open in February 2027.
- First completions: Planned from April 2027.
The government has allocated £4.7 billion over five years to support the scheme.
Eligibility rules, property price caps and lender participation will determine who can apply.
Source: Your First Home: Official Government Guidance.
How Does the Your First Home Scheme Work?
The principle is straightforward.
Instead of borrowing almost the entire purchase price through a conventional mortgage, the buyer uses three funding sources.
These comprise their deposit, a mortgage and a government equity loan.
Consider a property costing £300,000.
| Funding source | Amount |
|---|---|
| Buyer deposit: 2.5% | £7,500 |
| Government equity loan: 20% | £60,000 |
| Repayment mortgage | £232,500 |
| Total property price | £300,000 |
A buyer purchasing the same property with a standard 95% mortgage would usually need a £15,000 deposit.
Their mortgage would also be larger at £285,000.
Under Your First Home, the smaller mortgage could reduce monthly repayments.
However, the buyer would still owe the government equity loan.
That distinction is important.
Who Could Qualify for a 2.5% Deposit Mortgage?
The scheme targets eligible first-time buyers purchasing new-build properties in England.
Under current guidance, applicants will normally need to:
- Be first-time buyers.
- Purchase an eligible new-build home from a participating developer.
- Occupy the property as their main residence.
- Meet the relevant household income limit.
- Purchase within the local property price cap.
- Qualify for a mortgage from a participating lender.
The government has published different property price caps for local areas.
Therefore, eligibility may depend on where you intend to purchase.
Full application rules will follow before the scheme opens.
Importantly, a 2.5% deposit does not remove affordability checks.
Lenders will still assess income, spending, existing commitments and credit history.
Our first-time buyer mortgage guide explains these checks in greater detail.
The Important Detail: The Equity Loan Is Not Free Money
The government equity loan offers an interest-free period.
This can improve initial affordability.
However, the loan represents a percentage of the property’s value.
The government will normally expect repayment of the same percentage of the home’s value when the equity loan is repaid.
Imagine buying a property for £300,000.
Your government equity loan is £60,000, representing 20% of the purchase price.
Several years later, the property has increased in value to £320,000.
If you repay the full equity loan at that valuation, the amount would normally be £64,000.
You would repay more than the original £60,000 because the property value increased.
Conversely, a fall in property value could reduce the amount repayable.
The government therefore shares in the property’s increase or decrease in value.
This is different from a conventional mortgage with a fixed capital balance.
What Happens After the Interest-Free Period?
The published scheme guidance sets out the following equity loan interest rates:
| Period | Equity loan interest |
|---|---|
| Years 1–5 | 0% |
| Year 6 | 1.5% |
| From year 7 | 3% |
Interest payments do not reduce the equity loan balance.
They represent an additional cost alongside the mortgage.
Buyers should also consider the impact of property price changes, future remortgaging and eventual repayment.
A smaller mortgage today may come with a larger financial commitment later.
What Do Current House Prices Tell First-Time Buyers?
The latest completed-transaction figures underline why location remains important.
In August 2026, the average first-time buyer property price in England was approximately £246,000.
However, substantial regional differences remain.
London’s average first-time buyer price exceeded £473,000.
In the North East, it was approximately £145,000.
These figures come from the August 2026 UK House Price Index.
They cover first-time buyer purchases generally, not just qualifying new-build homes.
Therefore, they should not be treated as scheme eligibility limits.
Instead, they show why local research remains essential.
A buyer’s financial position, preferred location and property type can all change the available choices.
What About the Lifetime ISA Changes Announced in Budget 2026?
Budget 2026 also introduced changes affecting some first-time buyers who already hold a Lifetime ISA.
From 29 October 2026, a 20% withdrawal charge applies to qualifying first-home purchases above the £450,000 property price cap.
Previously, the charge was 25%.
The lower charge allows affected savers to keep their original contributions, but they will lose the government bonus.
Other unauthorised withdrawals generally remain subject to a 25% charge.
The government also plans to introduce a new First Time Buyer ISA from April 2029.
That future product is separate from the Your First Home equity loan scheme.
Existing Lifetime ISA holders can continue using their accounts under the applicable rules.
You can read the HMRC guidance on first-time buyer savings changes.
Is It Better to Wait Until 2027 to Buy?
The introduction of a new scheme creates an understandable question.
Should you buy now or wait?
That depends on your circumstances.
For some buyers, Your First Home may make a suitable new-build property more accessible.
Others may prefer an existing property or a conventional first-time buyer mortgage.
A 5% deposit mortgage could still be appropriate.
The right comparison should consider:
- Total borrowing and monthly repayments.
- The government’s equity loan repayment conditions.
- Interest charges after five years.
- Property value and long-term affordability.
- Mortgage fees and other purchase costs.
- Whether the property meets your needs.
You can explore repayment scenarios using our residential mortgage affordability calculator.
A calculator provides an initial estimate, not a mortgage offer.
Frequently Asked Questions
Can I apply for Your First Home in November 2026?
No. Applications are not yet open. The government expects pre-registration to open before the end of 2026, with applications opening in February 2027.
Does the government own part of my property?
You own your home. However, the equity loan is linked to the property’s value and must be repaid under the scheme’s conditions.
Can I use Your First Home to buy an older property?
No. The scheme currently targets eligible new-build properties in England.
Is a 2.5% deposit enough to guarantee a mortgage?
No. Applicants must satisfy the scheme requirements and the lender’s affordability, credit and property checks.
A First Home Should Be Affordable Beyond the First Five Years
Buying your first property represents more than receiving the keys.
It creates a long-term responsibility.
Your First Home could help some buyers overcome the initial deposit barrier.
However, the real measure of affordability is whether the arrangement remains suitable as circumstances change.
At Connect Mortgages, our advisers can help first-time buyers compare conventional mortgages and available government-supported options.
We can also explain the lender checks, costs and financial commitments involved.
Before deciding whether to wait for Your First Home, understand what you could already afford today.
Speak to a Connect Mortgages adviser about your first-home options.
Your home may be repossessed if you do not keep up repayments on your mortgage or other loans secured on it.
Information correct as at 17 November 2026. The Your First Home scheme is not yet open, and full terms remain subject to further government guidance.